
Unlocking the Equity in Your Home: How a 2nd Mortgage Works in Canada
SC
In Canada, many homeowners are discovering the potential benefits of unlocking the equity in their homes through a second mortgage. This financial tool can provide access to funds for various purposes, from home renovations to debt consolidation. Understanding how a second mortgage works is crucial for making informed financial decisions.
What is a Second Mortgage?
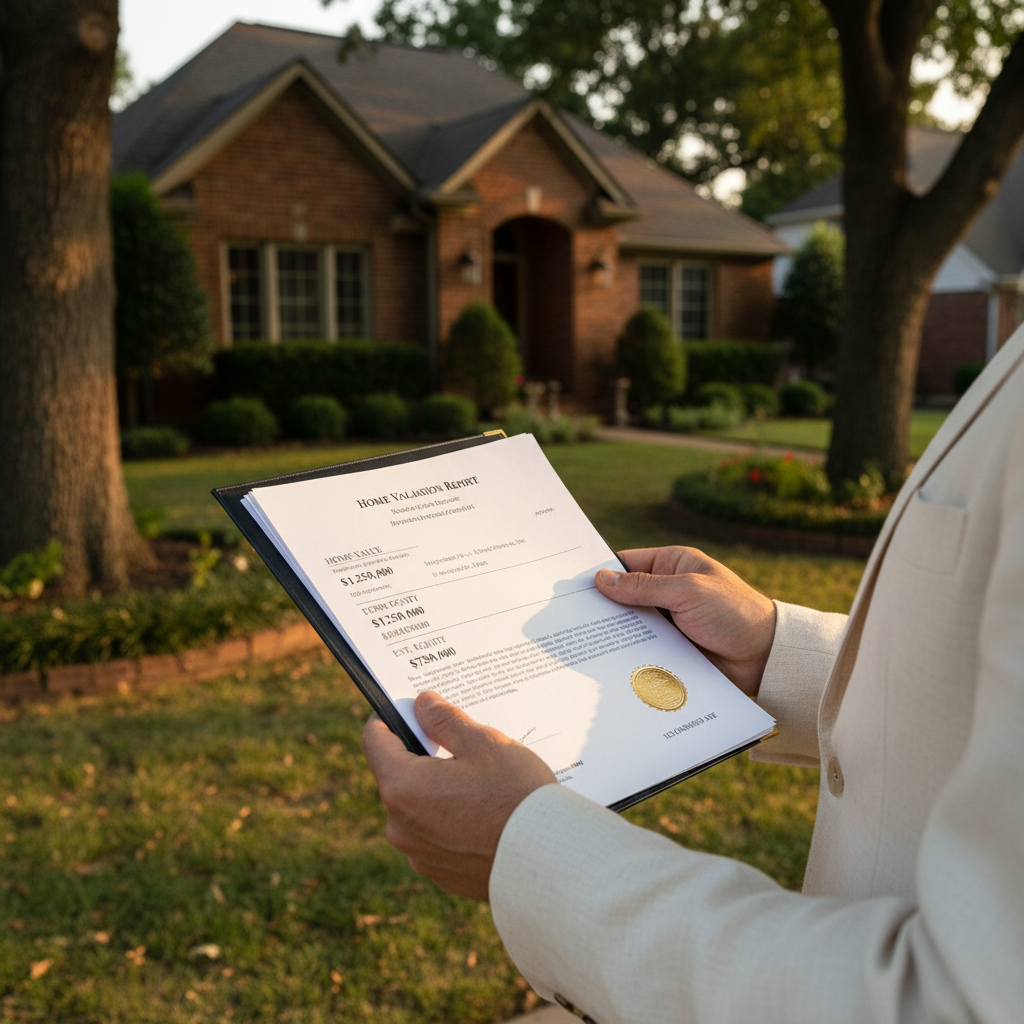
A second mortgage is a loan taken out on a property that already has an existing mortgage. It allows homeowners to borrow against the equity they've built up in their home. The equity is the difference between the current value of the property and the remaining balance on the primary mortgage.
How Does It Work?
When you apply for a second mortgage, lenders assess the equity in your home to determine how much you can borrow. Typically, lenders allow you to borrow up to 80% of the home's appraised value, minus the amount you owe on your first mortgage. This type of loan is secured by your property, making it a less risky option for lenders compared to unsecured loans.
Second mortgages come in two main types:
- Home Equity Loan: Provides a lump sum of money upfront with a fixed interest rate and repayment term.
- Home Equity Line of Credit (HELOC): Offers a revolving credit line that you can draw from as needed, similar to a credit card.
Benefits of a Second Mortgage
One of the main advantages of a second mortgage is the ability to access funds at a lower interest rate compared to other types of loans. Because the loan is secured by your home, interest rates are generally lower than unsecured debt options like credit cards.
Additionally, a second mortgage can provide a substantial amount of money that can be used for various purposes, such as home improvements, educational expenses, or even starting a business. It can also be an effective way to consolidate higher-interest debts, potentially reducing your overall monthly payments.
Considerations Before Taking a Second Mortgage
Before deciding on a second mortgage, it's important to consider several factors. First, assess your financial situation to ensure that you can manage additional monthly payments. Keep in mind that if you default on the loan, you risk losing your home.
It's also wise to compare different lenders and their terms. Look for competitive interest rates and flexible repayment options that suit your needs. Consulting with a financial advisor can also provide valuable insights based on your specific circumstances.
Steps to Apply for a Second Mortgage
Applying for a second mortgage involves several key steps:
- Assess your home equity to determine the amount you can borrow.
- Research and compare lenders to find the best rates and terms.
- Gather necessary documentation, such as proof of income and property appraisal.
- Submit your application and await approval from the lender.
- Review the loan agreement carefully before signing.
Unlocking the equity in your home through a second mortgage can be a powerful financial strategy when used wisely. By understanding how it works and evaluating your options, you can make decisions that align with your long-term financial goals.