
The Benefits of a 2nd Mortgage: Unlocking Home Equity
SC
Understanding a 2nd Mortgage
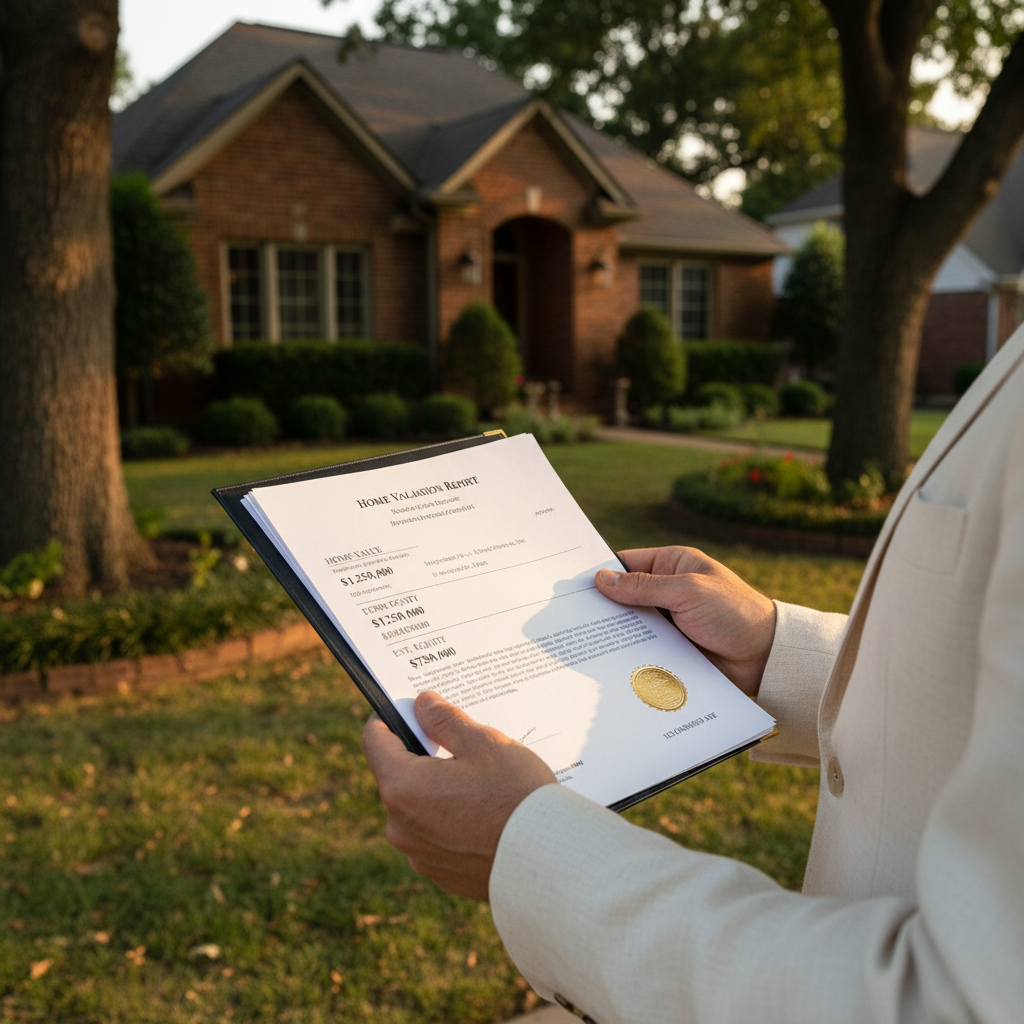
A 2nd mortgage, often referred to as a home equity loan or line of credit, allows homeowners to borrow against the equity they have built in their property. This financial tool can be beneficial for those looking to access funds for various purposes. Unlike the primary mortgage, a 2nd mortgage is subordinate, meaning it is only paid off after the first mortgage in the event of a default.
Homeowners usually consider a 2nd mortgage to unlock the value that has accumulated in their homes over time. This equity can be leveraged to improve financial flexibility and achieve personal goals. Whether you're looking to renovate your home, pay for education, or consolidate debt, a 2nd mortgage might be a viable option.
Key Benefits of a 2nd Mortgage
Access to Significant Funds
One of the primary advantages of a 2nd mortgage is the ability to access a substantial amount of money. Since these loans are secured by the value of your home, lenders are often willing to offer larger sums compared to unsecured loans. This can be particularly useful for funding major expenses like home improvements or significant life events.
Potential Tax Advantages
In many cases, the interest paid on a 2nd mortgage may be tax-deductible, which can provide additional financial relief. It's essential to consult with a tax advisor to understand how this applies to your specific situation and ensure you maximize any potential benefits.
Flexible Repayment Options
2nd mortgages often come with flexible repayment terms, allowing homeowners to choose between fixed-rate and variable-rate options. This flexibility can help in managing monthly payments and aligning them with your financial circumstances. Fixed rates provide stability, while variable rates might offer lower initial payments.
Improving Credit Score
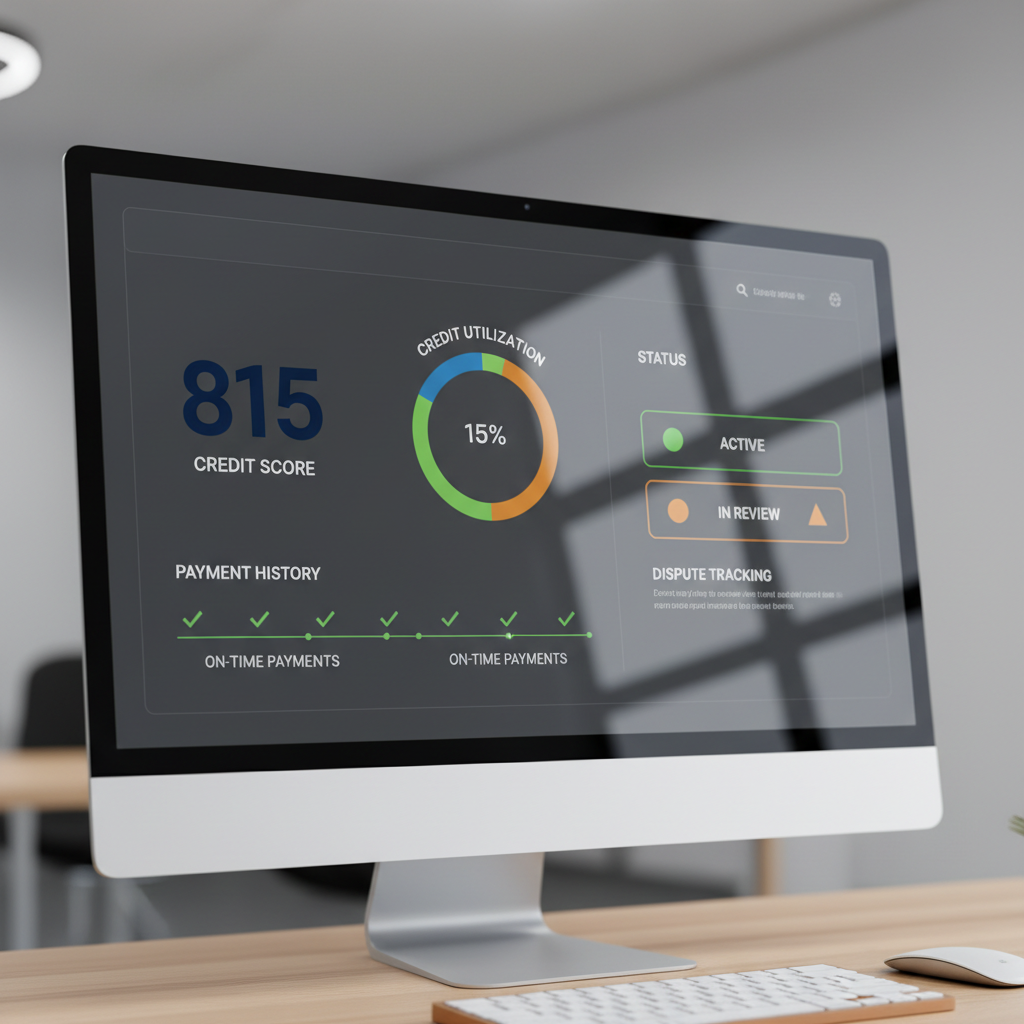
Using a 2nd mortgage to consolidate high-interest debts can improve your credit score over time. By paying off credit cards and other debts, you can reduce your credit utilization ratio, which is a key factor in credit scoring. This strategic move can lead to better financial health and open up more opportunities in the future.
Considerations Before Taking a 2nd Mortgage
While a 2nd mortgage can offer numerous benefits, it's crucial to weigh the risks involved. Since your home is used as collateral, failing to meet repayment obligations can result in foreclosure. It's vital to assess your financial situation and ensure you have a solid plan in place before proceeding.
Another important consideration is the cost associated with a 2nd mortgage. There may be fees, closing costs, and other expenses that need to be factored into your decision. Comparing offers from different lenders can help you find the most favorable terms.
Conclusion: Unlocking Potential
A 2nd mortgage can be a powerful tool for unlocking your home's equity and achieving financial goals. By understanding the benefits and risks, you can make an informed decision that aligns with your long-term objectives. Whether you're looking to invest in home improvements, manage debt, or fund important life events, a 2nd mortgage might be the key to unlocking new opportunities.