
Common Mistakes to Avoid When Applying for a 2nd Mortgage
SC
Understanding a Second Mortgage
Applying for a second mortgage can be a strategic move to access additional funds. However, it requires careful planning and understanding of the terms and conditions. A second mortgage allows homeowners to borrow against their home equity, but there are common mistakes that can complicate the process.
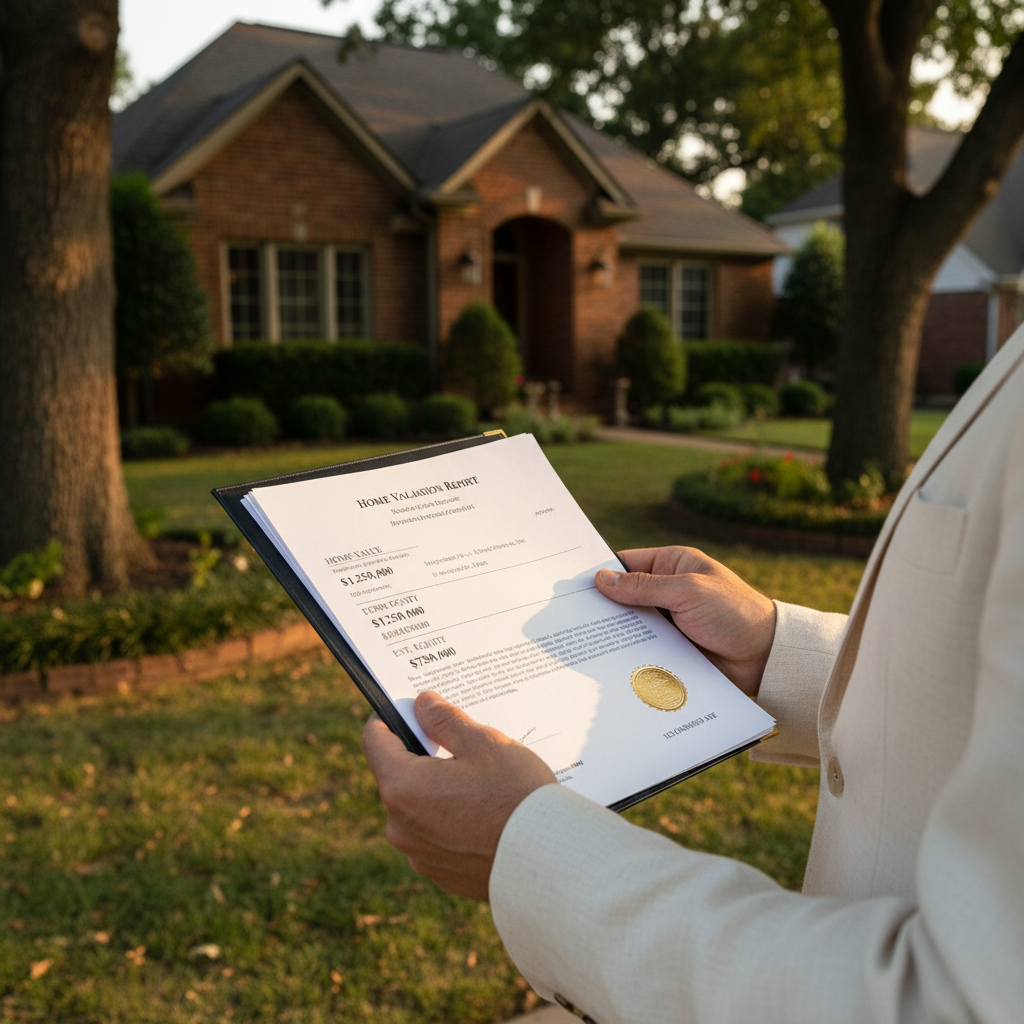
Overestimating Your Home’s Value
A frequent mistake is overestimating the value of your home. This can lead to borrowing more than you can realistically afford. Ensure you get a professional appraisal to have an accurate valuation. Accurate numbers are crucial for making informed decisions.
Ignoring Additional Costs
Many applicants overlook the additional costs associated with a second mortgage. These can include appraisal fees, application fees, and closing costs. Understanding all potential expenses helps prevent unexpected financial burdens.
Evaluating Your Financial Situation
Before applying, it’s important to thoroughly evaluate your financial situation. This involves assessing your current debts, income stability, and credit score. A poor credit score can lead to higher interest rates.
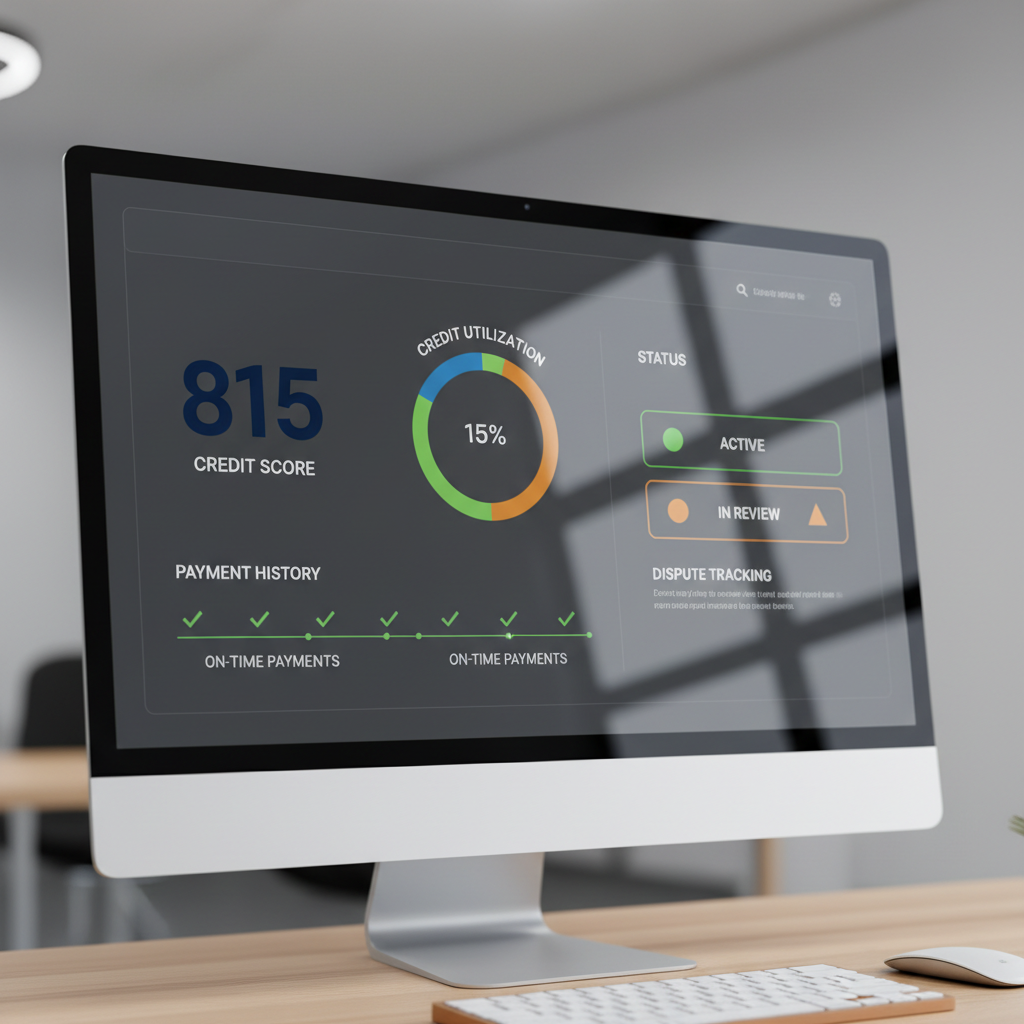
Not Comparing Lenders
Another common mistake is not shopping around for the best lender. Different lenders offer varying terms and interest rates. Comparing offers ensures you get the most favorable conditions for your financial situation.
Overborrowing
Borrowing more than necessary is a trap many fall into. It’s tempting to take advantage of your home equity, but it’s vital to borrow only what you need. This helps in maintaining manageable repayment terms.
Preparing Proper Documentation
Proper documentation is essential for a smooth application process. Missing or incorrect documents can lead to delays or even rejection. Ensure you have all the necessary paperwork, such as proof of income, tax returns, and property details.
Neglecting to Plan for the Future
While focusing on immediate financial needs, it’s easy to forget about the future. Consider how taking a second mortgage will affect your financial plans, including retirement and long-term savings. Planning ahead prevents potential financial strain down the road.
Conclusion
A second mortgage can be a valuable financial tool when used wisely. By avoiding these common mistakes, you can navigate the process more smoothly and secure the best terms for your situation. Being informed and prepared is key to making the most of your home equity.